 1
Find deals through local relationships
We source homes through Amin Realty and relationships built over years with Detroit investors and wholesalers. This local network helps us find opportunities for the fund.
Fajr Income Fund · Reg D 506(c) · Accredited investors only
Debt-free Detroit rentals. We find the deals and manage them. You collect the income.
$50,000 minimum*
Ready for a closer review? Request the offering documents.
First tranche closes November 30.*
1% annual management fee on contributed capital.*
 Nabil SyedCEO
 Faseh MohammedCOO
 Shams MerchantLegal Counsel, CRE.law
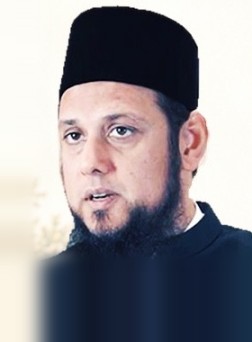 Mufti Aasim RashidIslamic compliance advisor
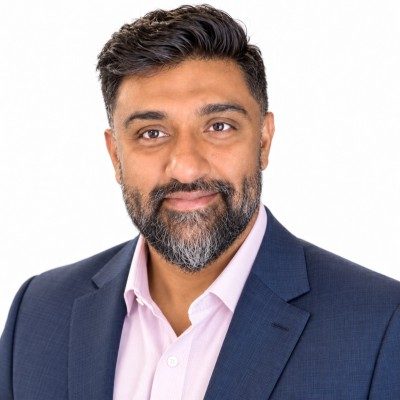 Abdul Wahid KhanStrategic Advisor1
We source homes through Amin Realty and relationships built over years with Detroit investors and wholesalers. This local network helps us find opportunities for the fund.
 2
Omni Property Managers inspects each home and reviews its condition and repair needs. Homes the team approves then move to Fajr for a full financial review.
 3
Fajr reviews the price, repairs, expected rent, expenses and reserves against the fund’s buying standards. When a home meets our criteria, we buy it all cash.
Buying with cash helps us close faster and negotiate prices that work for the fund.
Fajr Fund I (FF1), our closed Legacy Fund. Not the current offering.*


“Nabil and Faseh were through in explaining the fund process and I get monthly updates and all properties details are available easy access website portal. Looking forward to the next fund.”
“Investing with IRA was straightforward and I am happy that my money is out of stock market volatility and can enjoy stable income without the landlord hassle.”
“I wanted to invest in Detroit’s upcoming market but was scared to invest in house not knowing who would maintain it. Happy to have invested on Fajr fund 1 and get same benefit …”
Fajr Fund I investors. Not a guarantee of future results.*
Real assets in a market we know locally: debt-free, execution-led, with an income-first approach.
28 FF1 properties tracked, 22 held, 6 sold (as of October 8, 2026).
Affiliated brokerage for sourcing, market intelligence, broker relationships, and transaction flow.
Title coordination, closing support, and transaction confidence.
Affiliated property management for leasing, maintenance and tenant relations.
Investor relations, governance, reporting cadence, and disciplined allocation process.
A cost segregation study splits a rental into parts (appliances, flooring, fixtures). Eligible parts can take 100% bonus depreciation up front. Land and the building shell can’t. That deduction can offset passive income.
Hypothetical example*: $100,000 invested → $50,000 deduction
$12,500 potential tax savings over three years.
CEO
Born and raised in Detroit. 10 years and $150M+ in real estate deals. He buys every Fund property in neighborhoods he knows block by block.
COO
An engineer who has taken part in $70M+ of real estate. He runs investor capital and reporting, so you always know where your money is and what it's earning.
We invest our own capital alongside LPs.
Segregated for charity, net of recovery costs.
Sponsor’s stated giving commitment.
Giving comes from the sponsor’s share. It does not reduce LP distributions or create an LP charitable deduction.
Late-fee donations are net of documented third-party collection and enforcement costs. The stated 5% policy sits within the PPM’s discretionary allowance of up to 5% of defined Net GP Profits.
You buy a share of a fund that plans to own rental properties. Think of it as a shared basket of properties. The team chooses and runs the properties using its on-the-ground knowledge of Metro Detroit. Most purchases are planned for that area because it is where the general partners have local experience. You own a piece of the fund, which owns the properties, rather than holding the deed to one house yourself.
The usual minimum is $50,000; smaller amounts need the fund manager’s approval. Buyers must meet an investor eligibility standard called accreditation. It looks at income, net worth, or certain licenses. The fund must check that status as part of the joining process, and we can explain the steps.
FIF is designed to be halal, with real property ownership and no interest-based property borrowing. Certification is in progress: we are engaging a renowned Islamic scholar to review the structure and guide any needed fine-tuning. Our plan is to complete certification before launch and share the written certification once it is issued.
It gives you first place for a share of money the fund can pay out. It is called a preferred return. Eight percent of $100,000 is $8,000 for a full year, or $2,000 for a quarter, in simple math. Investors receive this share before the GP receives rental profits, subject to cash being available.
| If cash is available in this simple example | What happens |
|---|---|
| $2,000 for your share of the quarter | You could receive $2,000 toward that quarter's preference. |
| $500 for your share of the quarter | You could receive $500; the unpaid $1,500 keeps its place for later. |
| $0 for your share of the quarter | The quarter’s $2,000 preference carries forward for payment from future available cash. |
This table ignores other investors and fees to show the idea. The unpaid amount does not earn extra interest.
Our current operating plan targets January 2027 for launch, roughly 90 days to put capital into homes, and a first payment around June 2027 if enough cash is available. For someone investing in January, that means planning for roughly six months before the first check. It is a target, not a fixed six-month promise for every investor.
The timing for earning the preferred return is separate. The first tranche is scheduled to close November 30, 2026, and the preference starts March 1, 2027 for money received and accepted by then. Later investments have an adjustment rule. Any revised dates must appear in the updated fund documents. Cash payments depend on the money available.
This is a long-term investment in real homes, which take time to sell. It is “illiquid”: you cannot demand an early cash-out. The target hold is five years from the first purchase, with up to two one-year extensions. If you need the money before five years, this investment is probably not a good fit.
Yes. We reduce risk by targeting finished, rent-ready homes with sound structures and systems suited to our five-year plan. We inspect them and budget for repairs. Owning without mortgages removes loan payments and refinancing pressure, but unexpected costs, unpaid rent, or lower sale values can still cause a loss of some or all capital.
Nabil and Faseh lead the fund. GP means the team running it; LP means an investor. Property managers, a brokerage, and a title company may also provide services and earn fees. Related businesses and their fees are disclosed in the PPM, the detailed offering document, and their service agreements set out the work they must perform.
The GP earns a management fee of 1% a year on contributed investor capital, paid quarterly. For $1 million contributed, that is $10,000 a year, or $2,500 a quarter. Separate property and transaction service fees are additional costs. For rental profits, investors come first: after all costs, fees, and reserves, the fund pays their 8% annual preferred return, including any unpaid amount from earlier periods. The GP receives the remaining rental profit. Eight percent a year is 2% for a full quarter in simple math. If less than that is available, the GP receives no rental profit share that quarter.
| GP profit-share example: $1 million contributed | A full quarter, after costs, fees, and reserves |
|---|---|
| $15,000 left (1.5%) | Investors receive $15,000; the GP receives $0 of profit share. The unpaid $5,000 preference carries forward. |
| $25,000 left (2.5%) | If no earlier preference is unpaid, investors receive $20,000 and the GP receives the remaining $5,000. |
You can invest personal cash or use an eligible self-directed retirement account, including a traditional IRA or Roth IRA. “Self-directed” means the account can hold investments such as private real estate funds. A custodian holds and administers the IRA. We currently plan to work with Rocket Dollar and American IRA as provider options, subject to their acceptance of the investment and account setup. The IRA owns the fund interest, and payments return to the IRA.
Start by letting us know. We will help you understand the fund, answer your questions, and guide you through the paperwork. Our current plan is to complete investor decisions before November 30, 2026, with an operating launch in January 2027.
| Step | What happens |
|---|---|
| 1. Review the pitch deck | We send you a short overview of the homes, strategy, expected returns, and team. |
| 2. Talk with the fund managers | If you have questions after reading it, we arrange a call to walk through them. |
| 3. Review the full documents | We send the PPM and related fund documents. Read them yourself and, if you wish, with your attorney or financial adviser. |
| 4. Confirm your interest and allocation | Aim to complete your review before November 30, 2026. Allocations are handled first come, first served, subject to available space, eligibility verification, signed subscription documents, and the fund’s acceptance. |
| 5. Prepare and send your investment | We discuss your proposed allocation on a call and help you get funds ready. We plan to provide wiring instructions by November 30. Follow the written funding deadline; retirement-account payments go through the account’s provider. |
| 6. Get ready for launch | Our operating launch target is January 2027, followed by property deployment and investor updates. See the payment-timing answer for the first-distribution target. |
A call confirms the next steps; the accepted subscription documents confirm your investment. If using retirement funds, start the account and transfer process early so the provider has time to complete it.
The intro call is structured, direct, and honest. We'll cover the model, answer questions, and determine together if it's the right fit.
No pressure, no pitch. 30 minutes to see if it fits your goals.
Targets, not guarantees. Capital is at risk.
Distributions and returns are targets, not guarantees. Capital is at risk; distributions may vary or stop.
This page explains the fund and uses hypothetical examples, not guaranteed results. The offering documents and accepted agreements govern your investment. Returns, capital repayment, and tax benefits depend on actual results and individual circumstances. Review personal tax questions with your own adviser.
Fajr Fund One properties. Past holdings do not assure future acquisitions or results.
Affiliate relationships and related-party transactions require disclosure, conflict review, and arm's-length discipline.
Sponsor-reported and unaudited. Sponsor and affiliate experience is not Fajr Income Fund performance.
We work with an Islamic compliance advisor to review our fund structures and documents. Any determination of compliance is specific to the relevant offering and its final documentation; this website does not imply certification.